All Categories
Featured

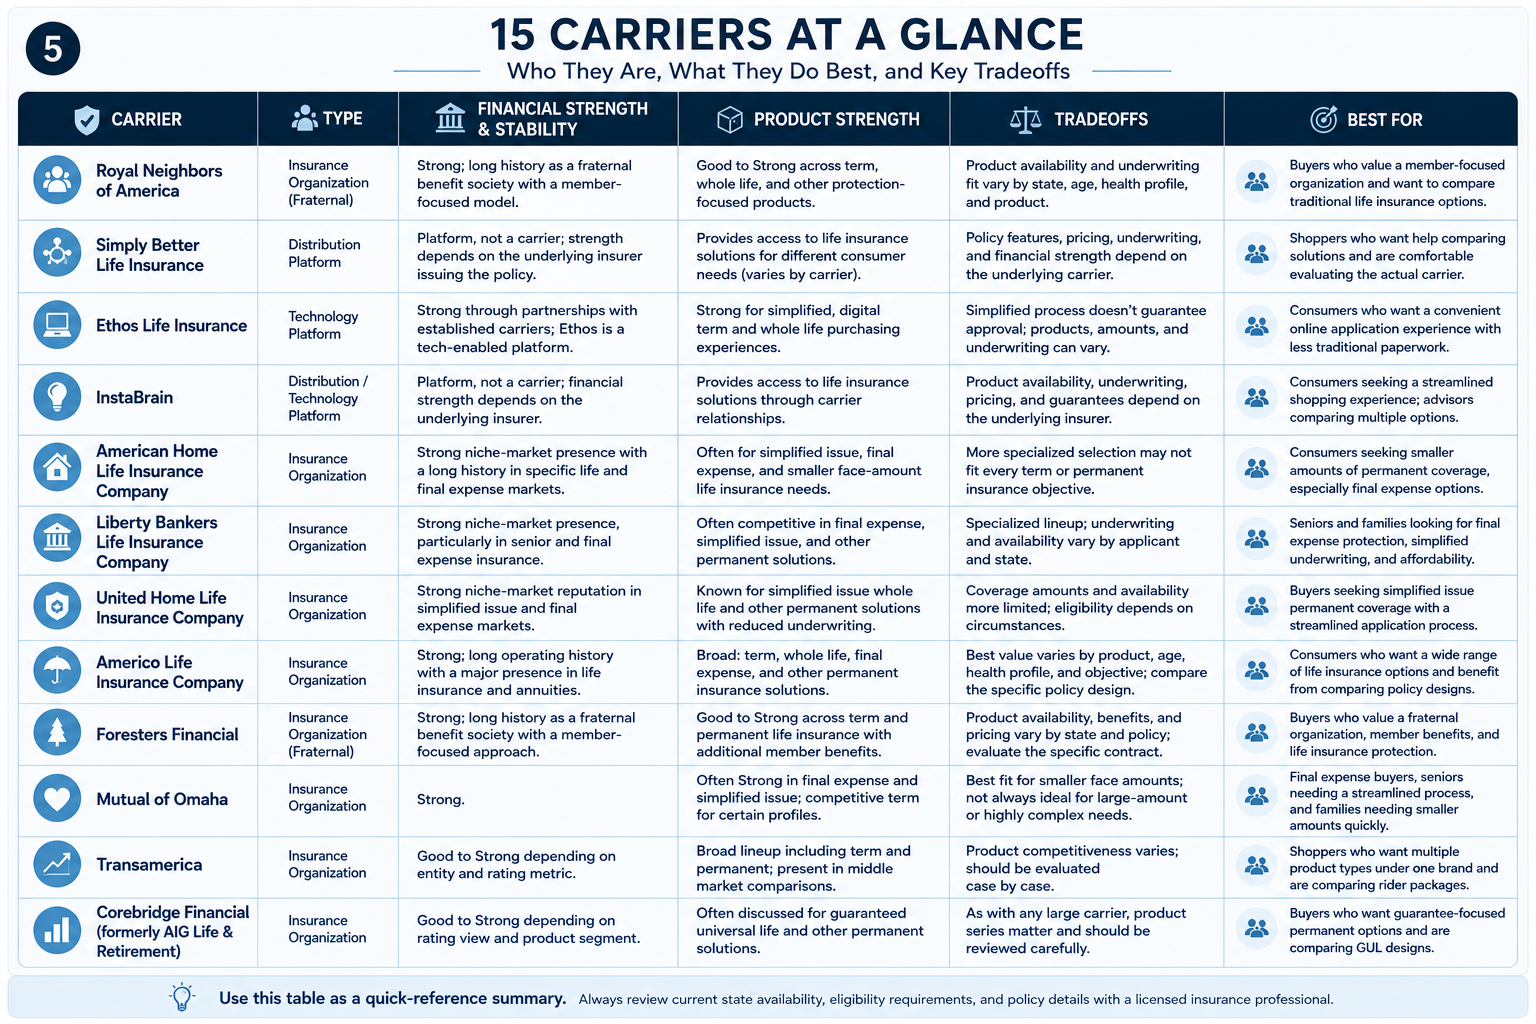
Indexed Universal Life Insurance Benefits for Future Security
Table of Contents
How much coverage does my family really require, based upon earnings, financial obligations, and dependents? Am I still within my VGLI eligibility window particularly, the 240-day no-health-review period? Do I have a service-connected disability that could make me eligible for VALife? Would I certify for more beneficial rates through a private insurance company, or would health.
concerns work versus me? Do I desire term coverage, long-term protection, or a mix? What protection do I already have through VGLI, VALife, a company, or existing savings that should factor into the overall? Am I comparing programs based upon my real eligibility, not simply general assumptions about age or health? No. VGLI is the separate group term program available to eligible veterans after they leave service it's developed to select up where SGLI leaves off, but you have to look for it individually, within a specific window. For a closer look at SGLI itself, consisting of how it compares to personal protection while you're still serving, see SGLI vs. Yes. VGLI premiums are based upon your age and the quantity of coverage you choose, and rates generally increase at older ages. has existing rate info. Yes. VA explicitly allows obtaining both. Numerous veterans utilize this to get more total protection than VGLI alone supplies, or to compare their alternatives. VGLI, by comparison, is term insurance coverage, not entire life. There's no universal number it depends on your earnings, financial obligations, dependents, existing protection, and objectives. LifeCoverPath's calculator can assist you overcome those factors and get an individualized, instructional estimate. No. LifeCoverPath is an independent.
academic resource operated by VetLife LLC as part of its Veteran Life Insurance coverage company. Department of Veterans Affairs, the U.S. armed force, or any federal government company. For present rates, eligibility rules, and applications, always go directly to VA's own resources:. You complete life insurance coverage starts 2 years after you apply.
Strategic Term and Whole Life Insurance Strategies
You should pay the premiums throughout those two years. If you pass away during the 2 year waiting duration, they will pay your recipients the overall quantity you paid in premiums, plus 10 %interest. If you pass away anytime after the 2 year waiting period, your recipients will be paid the full coverage amount of your policy. Veterans deal with special moneyrequirements, so life insurance coverage is very important. To discover the best coverage, it is essential to understand VA advantages and pensions. Term life insurance coverage offers cost effective protection for a restricted time. Entire life insurance coverage provides protection for life and might develop cash value. Veterans need to choose versatile policies and examine for sped up survivor benefit. Browsing life insurance can be difficult, especially for veterans returning to civilian life. Choosing the right insurance plan is a huge choice, with veterans dealing with particular needs. This guide will look at why life insurance coverage policies matter for veterans. It will likewise discuss the various types of policies you can get and important things to remember when picking coverage. Life insurance coverage is a fundamental part of financial planning. It functions as a security net for enjoyed ones if the policyholder dies. This is particularly essential for veterans since they face distinct difficulties after serving their country. While military service provides a sense of purpose and team effort, returning to civilian life can be tough. Life insurance is a required security, offering financial security and assurance throughout these modifications and later. By finding out more about life insurance, veterans can make wise options to secure their families'monetary future. Veterans frequently face various money circumstances that require mindful thought about life insurance coverage. Many veterans leave the military when they're still young. This change can include earnings ups and downs or job modifications. They may need to rethink their long-lasting cash strategies. For veterans with families, especially those who have dependent children, it is very important to ensure their liked ones are economically safe. Life insurance acts as a security internet. It ensures that recipients, like partners and children, are secured if the veteran dies.
Life insurance provides veterans and their families crucial security and peace of mind. The death benefit, some life insurance coverage policies, like entire life insurance, construct cash value over time. The two main types are term life insurance and long-term life insurance coverage.
Term life insurance enables insurance policy holders to change coverage as they need. While term life insurance is great for momentary requirements, it's crucial to believe about if you might require defense for your entire life, specifically as a younger veteran. Whole life insurance coverage is a kind of long-term life insurance.
This helps offer peace of mind throughout bumpy rides. Life insurance coverage gives veterans and their families crucial security and peace of mind. It generally does this by providing a monetary safeguard. This takes place through a tax-free death advantage that goes to chosen recipients when the policyholder passes away. This cash assists liked ones handle the expenses that feature
Cheap Individual Health Insurance Quotes in the US
losing their primary earnings earner. Besides the survivor benefit, some life insurance policies, like entire life insurance, build money value with time. This cash value grows without being taxed until you take it out. This function can be an excellent monetary tool. You can utilize it for additional income in retirement, paying for your child's education, or managing unexpected costs. They must believe about things like financial obligations, just how much money their dependents will require, and their general monetary goals. Dealing with a monetary consultant who understands veterans can truly assist in this procedure. This careful check helps guarantee that veterans get enough coverage to safeguard their households without facing high costs. Choosing how much coverage you require really depends upon your individual circumstance and monetary obligations. An excellent guideline is to look for coverage that is several times your annual earnings. This assists guarantee your member of the family can keep their method of life after you're gone. Keep in mind, this is just a beginning point. Consider costs for raising a family, like child care and education. Your private life insurance coverage ought to match these financial duties so your beneficiaries have sufficient support. The primary goal is to change your earnings and produce a safeguard for the future, so you and your enjoyed ones can feel safe and secure and not stressed out. These include impairment payments, healthcare services, and aid with education. These benefits are essential for veterans'health and happiness. However, it is also important to consider how they affect life insurance needs. For instance, veterans getting VA disability advantages or military pensions might not require as much cash if they die. Each policy has unique functions and advantages. The 2 main types are term life insurance coverage and permanent life insurance. It is crucial to understand the distinctions between these types so you can choose the best one for your financial goals, household needs, and spending plan.
Insurance Pricing RangesTerm life insurance coverage enables policyholders to change coverage as they require. While term life insurance coverage is fantastic for momentary needs, it's important to think about if you may need defense for your whole life, particularly as a younger veteran. Whole life insurance coverage is a kind of irreversible life insurance coverage.

Latest Posts
Indexed Universal Life Insurance Benefits for Future Security
Effective Ways to Secure 2026 Health Coverage
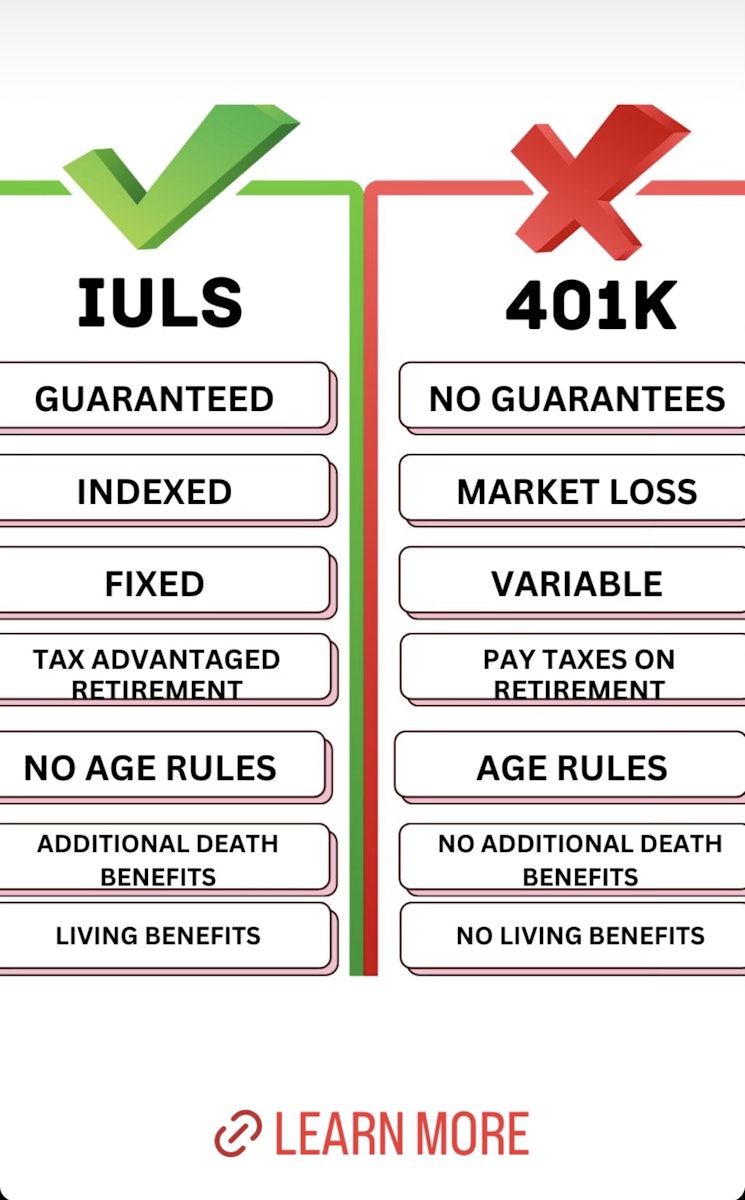
Final Expense Insurance Benefits